

How Large Cap Mutual Funds Perform During Market Volatility
Large-cap mutual funds are often described as the “safer” part of equity investing. But safer than what, and over which period?
During a market correction, a large-cap fund can lose money because it still owns equities. What it may offer is a more manageable ride than portfolios tilted towards smaller companies, not protection from losses.
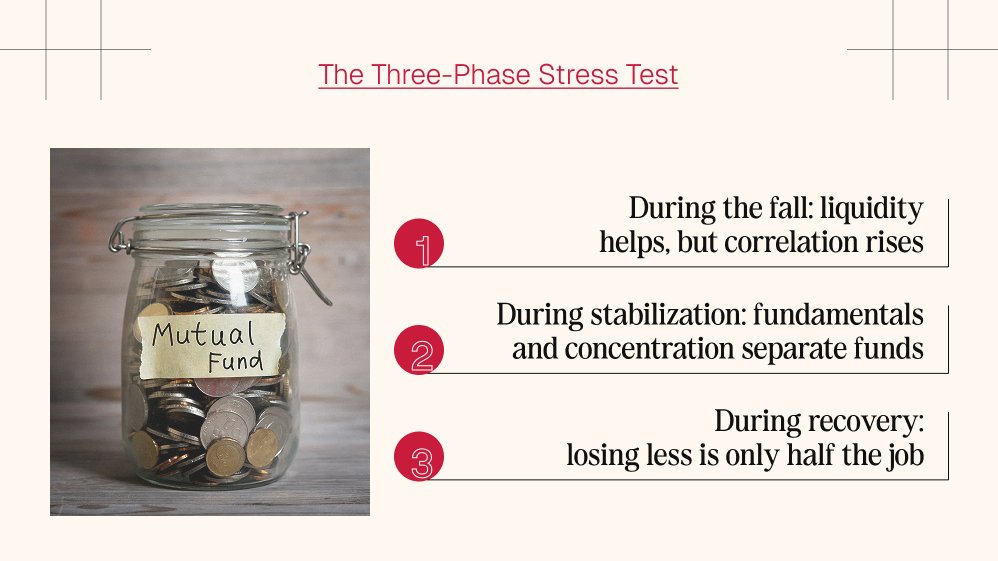
Understanding volatility in mutual funds therefore requires looking beyond the fall itself. The better test is how a fund behaves through three stages: the sell-off, stabilization, and recovery.
A fund that falls less but repeatedly trails its benchmark after fees may protect emotions better than wealth. One that declines with the market yet recovers efficiently may be fulfilling its mandate.
First, What Qualifies as a Large-Cap Fund?
Under SEBI’s scheme-categorisation framework, large-cap companies are those ranked 1st to 100th by full market capitalization. A large-cap mutual fund must invest at least 80% of its assets in equity and equity-related instruments.
This is a size rule, not a quality certificate. A large company can still carry high debt, face governance problems, suffer an earnings shock, or trade at an excessive valuation. Investors should not confuse market capitalization with resilience.
The Three-Phase Stress Test
| Market phase | Typical large-cap fund behavior | Why it happens | What investors should examine |
| Sharp sell-off | NAV normally falls, although often less than smaller-cap portfolios | Large stocks tend to have deeper liquidity, broader ownership and more established businesses | Maximum drawdown and downside capture versus the correct benchmark |
| Stabilisation | Prices may settle sooner as institutions return to liquid market leaders | Investors prefer companies with visible cash flows and easier price discovery | Sector exposure, valuation and whether the manager changed strategy |
| Recovery | Gains may be steadier, but the fund can lag if risk appetite shifts to mid- and small-caps | Smaller businesses often rebound faster in liquidity-driven rallies | Recovery time, upside capture and rolling returns after costs |
1. During the fall: liquidity helps, but correlation rises
When fear spreads, investors often sell what they can. Large-cap shares generally trade in greater volumes, helping managers meet redemptions without relying on hard-to-trade holdings. In a systemic shock, equity correlations rise, so diversification across large companies does not eliminate market risk.
Recent index data illustrates the relative, not absolute, advantage. In its July 31, 2026 factsheets, NSE Indices reported a one-year annualized standard deviation of 13.82% for the Nifty 50. Versus 18.27% for the Nifty Midcap 50 and 20.12% for the Nifty Smallcap 100. These index statistics are not promises for any fund.
2. During stabilization: fundamentals and concentration separate funds
Once indiscriminate selling slows, differences emerge. A diversified fund holding reasonably valued companies may stabilize sooner than a concentrated fund exposed to an overvalued sector.
Benchmark concentration also matters. As of July 31, 2026, financial services represented 36.18% of the Nifty 50, while its three largest constituents accounted for roughly 27.4% of the index.
A fund that is underweight those leaders can lag even if its holdings perform acceptably. A fund that hugs the index, meanwhile, may offer little benefit after charging a higher fee.
Active management should earn its keep through valuation, position sizing, and risk control, not prediction.
3. During recovery: losing less is only half the job
Investors frequently judge a fund by its lowest point. Recovery time is equally important. Consider an illustrative example:
- Benchmark falls 20%; Fund A falls 14%. Fund A’s downside capture is 70%.
- Benchmark then rises 25%; Fund A rises 15%. Its upside capture is 60%.
Fund A cushioned the decline, but its weaker rebound leaves the investor below the benchmark across the full cycle. Defense must not permanently surrender recovery participation.
Why “Active” Does Not Automatically Mean Better in Volatile Markets
Volatility creates opportunities for active managers, but opportunity and execution differ. The SPIVA India Year-End 2025 scorecard found that 75% of Indian active large-cap funds underperformed their benchmark over one year. The rates were 84.4% over five years and 76.3% over ten years.
This does not prove every index fund is superior. It means “professional management” is not evidence enough. Compare an active fund’s returns, risk, and costs with its total-return benchmark and a low-cost passive alternative.
The Metrics That Reveal What Returns Hide
Point-to-point returns can flatter a fund depending on the chosen dates. A stronger review of mutual fund volatility uses several measures together.
| Metric | What it answers | How to interpret it |
| Standard deviation | How widely did returns fluctuate? | Lower can mean a smoother ride; it does not identify the direction of returns |
| Maximum drawdown | What was the worst peak-to-trough fall? | Compare funds over the same market cycle |
| Downside capture | How much of the benchmark’s decline did the fund experience? | Below 100% suggests better downside containment |
| Recovery time | How long did the NAV take to regain its previous peak? | Shorter may signal resilience, but check the risk taken |
| Rolling returns | Was performance consistent across many start dates? | More informative than one-, three- or five-year point returns alone |
| Expense ratio and tracking error | How much return was lost to cost or benchmark slippage? | Particularly important when an active portfolio resembles its index |
Use the same plan type when comparing schemes, direct with direct, regular with regular. And prefer total-return benchmarks, which include dividends.
Should You Continue an SIP When Markets Turn Volatile?
A systematic investment plan buys more units when NAVs are lower and fewer when they are higher. That can improve the average purchase cost across fluctuating markets, but an SIP does not guarantee profit or prevent loss.
Stopping solely because prices fell can encourage buying when you’re confident and withdrawing when you’re fearful. Ask whether your goal, income, emergency reserve or risk capacity changed. Sound financial habits and a suitable asset-allocation process matter more than headlines.
Money needed within the next few years should not depend on a large-cap equity fund recovering on schedule. Even established companies can remain below previous highs for extended periods.
A Practical Large-Cap Fund Checklist
Before investing, or before exiting during a correction, check:
- Mandate: Does the portfolio consistently remain a genuine large-cap strategy?
- Full-cycle record: How did it perform during falls, recoveries, and sideways markets?
- Benchmark fit: Is the comparison against the scheme’s stated total-return index?
- Concentration: Could one sector or a handful of stocks dominate the result?
- Risk-adjusted outcome: Did lower drawdown come with acceptable recovery participation?
- Cost: Is any active advantage still visible after the expense ratio?
- Portfolio role: Does the fund complement your other equity holdings?
- Time horizon: Can the money remain invested for at least five to seven years?
Things Investors Should Not Miss In 2026
Large-cap mutual funds are shock absorbers, not safety vaults. Their scale, liquidity, and exposure to established businesses can moderate market swings, but the label alone says little about valuation, concentration, manager skill, or future returns.
The most useful way to evaluate volatility in mutual funds is across the complete market journey: how much the fund lost, how it behaved when conditions settled, and how effectively it participated in the recovery. Judge the process and the full-cycle outcome, not the calmest month or the most dramatic headline.
Disclaimer: This article is for general educational purposes and does not constitute investment, tax, or legal advice. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully and consider consulting a SEBI-registered investment adviser for guidance suited to your circumstances.

Must Read

Is Bankruptcy Right for You? Questions to Ask Before Filing in Georgia

How to Build a Modern Business Protection Strategy

Popular Street Bikes for Everyday Commuting

Head Of Growth Marketing Responsibilities: A Beginner’s Guide To The Role

How To Build A Growth Marketing Strategy That Actually Works
Most Popular

A Guide For Deductibles and Premiums in Accident Insurance
Financial Survival Tips for Entrepreneurs in Debt
Toronto Car Insurance vs. Other Cities: Why Are Rates So High?

The Future of MENA Businesses: Why You Need Both Management & Accounting Software



Leave A Reply